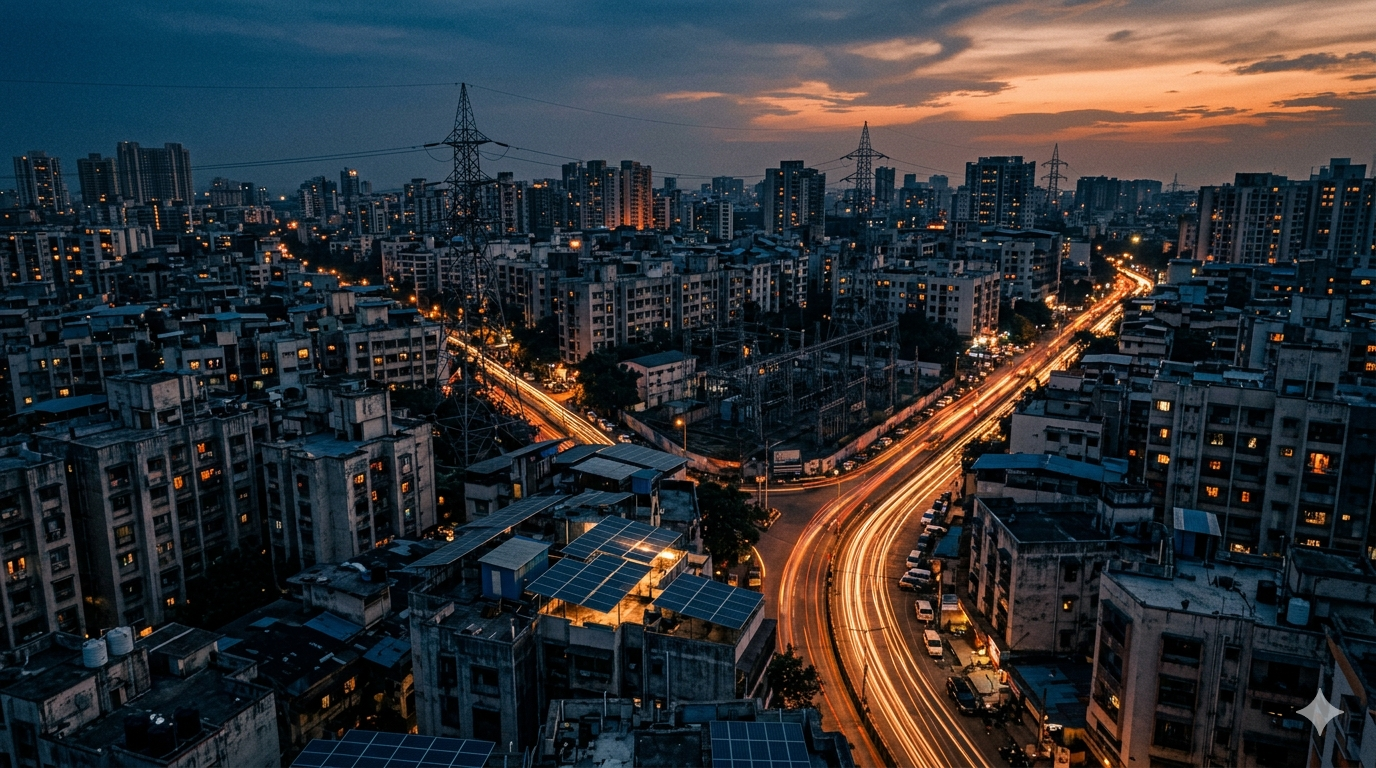
India's Urban Grids Were Not Built for This
Most of India's distribution infrastructure was designed in the 1970s and 80s for household lighting and appliances. The combination of rising air-conditioning loads, commercial electrification, and now EVs is pushing urban feeders toward their design limits. Studies by the Central Electricity Authority indicate that peak feeder loading in major metros already exceeds 85% of rated capacity during summer evenings — and EV adoption will add a further 15–20% load on urban feeders by 2030 if charging is unmanaged.
The traditional utility response — build more substation capacity — costs ₹8–15 Cr per 33/11 kV substation and takes 3–5 years from planning to energisation. Grid-edge technology offers a different answer: push intelligence and storage to the point of consumption, where it can absorb, shift, and shape load without waiting for utility capital cycles.
What Grid-Edge Actually Means in Practice
Grid-edge assets are anything deployed at or near the end consumer: rooftop solar, behind-the-meter batteries, smart inverters, and networked EV chargers. Their value comes not from any single asset but from the ability to coordinate them — responding to grid signals in seconds rather than months. Key capabilities the market is moving toward include:
- Demand flexibility: Smart EV chargers that can defer non-urgent sessions by 20–45 minutes under energy management system instruction, flattening the 6–9 pm peak.
- Behind-the-meter BESS: Co-located batteries that store cheap off-peak or solar energy and dispatch during peak periods, reducing both grid draw and demand charges.
- Smart inverter grid support: IEEE 1547-2018 compliant inverters that can provide reactive power support and voltage regulation — services that utilities currently pay peaking generators for.
International experience — from California's SGIP programme to the UK's Flexibility Market — shows that aggregated grid-edge assets can defer transmission and distribution upgrades worth 3–5x their capital cost. India's regulatory framework is beginning to recognise this through CERC's draft demand flexibility regulations.
The Opportunity for EV Charging Operators
For an EV charging operator, grid-edge capability is not just a technical feature — it is a business model differentiator. A hub that can guarantee a fixed peak demand draw regardless of how many EVs are charging simultaneously is far easier to connect to the grid, gets faster DISCOM approval, and qualifies for lower sanctioned load — reducing connection costs significantly.
EVBooth's integrated hardware and software platform is designed around this principle. Our Energy Management System coordinates charger scheduling, BESS dispatch, and solar generation in real time, with the goal of making every hub a predictable, grid-friendly asset rather than an unpredictable variable load. As we move toward launching our Hybrid Loop product in the coming months — currently in final site negotiations — this grid-edge coordination layer will be central to how these hubs operate.
Where India's Regulatory Framework Is Heading
CERC's 2024 draft Ancillary Services framework explicitly contemplates EV aggregators participating in frequency response markets. Several state DISCOMs are piloting demand response auctions. The pieces are coming together — what the market needs now is operators willing to build the grid-edge capability before the regulatory incentives are fully in place, because the operators who do will have a significant head start when they are.